Kenya’s agricultural sector could be entering a new phase of financing as the government seeks to place Savings and Credit Cooperative Organisations (SACCOs) at the centre of efforts to expand affordable credit for farmers and young agripreneurs.
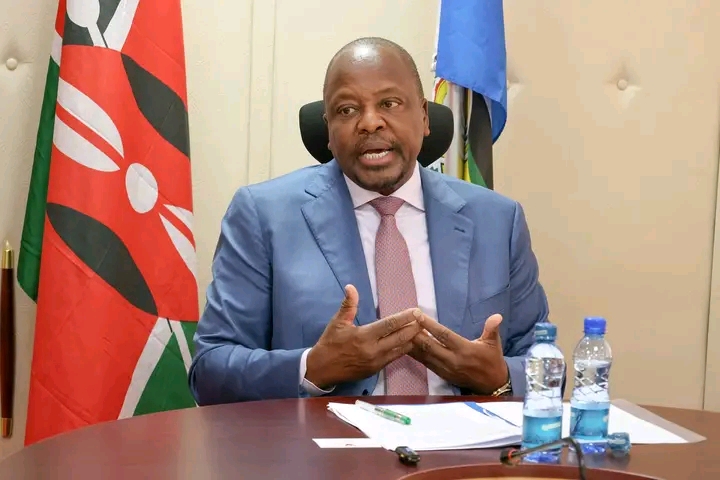
Agriculture Cabinet Secretary Mutahi Kagwe has challenged SACCOs to take a leading role in distributing agricultural loans, arguing that the cooperative movement offers an established platform for reaching farmers who struggle to access financing through conventional banking institutions.
The proposal comes as the government prepares to channel KSh 2.2 billion towards on-lending under the next phase of the Empowering Novel Business-led Employment (ENABLE Youth) programme, with SACCOs expected to serve as the primary financing channel.
Speaking during a progress review meeting with the African Development Bank (AfDB) and Ministry of Agriculture officials, Kagwe argued that agricultural enterprises cannot grow sustainably if farmers continue accessing expensive credit.
He maintained that agricultural financing should attract single-digit interest rates, warning that high borrowing costs could undermine efforts to make farming a profitable business.
The initiative also includes participating financial institutions, which have committed to mobilising an additional KSh 60 billion for young people and women through risk-sharing arrangements.
The announcement presents an opportunity to reconsider the role of SACCOs in Kenya’s agricultural financing landscape, particularly in supporting smallholder farmers, rural businesses and emerging agribusiness enterprises.
Why SACCOs matter in agricultural financing
SACCOs have traditionally played an important role in Kenya’s financial inclusion by mobilising savings and extending credit to members. Their presence in rural communities and established relationships with members could make them important partners in addressing agricultural financing challenges.
Unlike conventional financial institutions that may rely heavily on formal employment records and traditional collateral, SACCOs can build lending relationships around members’ savings histories, repayment behaviour and economic activities.
This provides an opportunity to develop financial products that respond to the realities of agricultural enterprises.
For instance, a dairy farmer may require financing to purchase improved cattle breeds, construct a livestock shed, acquire a chaff cutter or install water storage facilities. A young entrepreneur involved in poultry farming may need capital to construct housing structures, purchase chicks and invest in feeds.
Similarly, horticultural farmers require financing for irrigation systems, certified seeds, fertilisers, farm equipment and post-harvest handling facilities.
By understanding these different agricultural activities, SACCOs can develop loan products that support specific value chains rather than applying a uniform lending approach.
The potential of this model is supported by the sector’s existing financial reach. Government figures published in September 2025 indicated that membership in SACCOs regulated by the Sacco Societies Regulatory Authority (SASRA) had increased to 7.4 million, while their savings had grown to approximately KSh 786.99 billion.
Such financial resources provide an established foundation for expanding agricultural lending, provided that the institutions maintain sound financial management and adequate liquidity.
Expanding access to affordable credit for Young Agripreneurs
Access to affordable capital remains one of the major challenges facing young people interested in commercial agriculture.
Although agribusiness offers opportunities in crop production, livestock farming, food processing, transportation and marketing, many emerging entrepreneurs struggle to secure the initial investment required to establish sustainable businesses.
The ENABLE Youth programme seeks to address some of these challenges by combining enterprise incubation, business development support and access to financing.
According to the latest programme progress figures reported by the Kenya News Agency, eight Youth Agripreneurship Incubation Centres have been rehabilitated and equipped. Additionally, 1,500 young people have been recruited into incubation programmes, while another 1,000 have received support in developing bankable business plans.
This approach recognises that agricultural financing requires more than simply providing loans. Young entrepreneurs also need technical knowledge, financial management skills, market connections and mentorship to operate viable businesses.
SACCOs could strengthen this model by identifying promising enterprises within their membership networks and working with agricultural extension officers, incubators and other financial institutions to assess their financing requirements.
This would help bridge the gap between business development support and access to investment capital.
Turning SACCOs into agricultural investment partners
For SACCOs to become reliable agricultural financing partners, their involvement must extend beyond ordinary lending.
One opportunity lies in developing value-chain-specific financing products. Instead of offering general-purpose loans, SACCOs could introduce facilities targeting dairy farming, poultry production, horticulture, aquaculture and agro-processing.
Such products could incorporate repayment schedules that reflect agricultural production cycles and expected income from farm enterprises.
For example, farmers involved in seasonal crop production may need repayment arrangements that account for harvesting and marketing periods. Livestock enterprises, on the other hand, may require longer financing periods because investments in breeding animals, infrastructure and equipment take time to generate returns.
SACCOs could also collaborate with agricultural input suppliers, processors, cooperatives and produce buyers to strengthen the financing ecosystem.
Through these partnerships, farmers could access production inputs, technical assistance and reliable markets while financial institutions gain a better understanding of the businesses they are financing.
Risk-sharing arrangements involving participating financial institutions could further encourage lending to enterprises that would otherwise struggle to meet conventional borrowing requirements.
Addressing the risks of agricultural lending
Despite their potential, SACCOs face several challenges that could affect their ability to finance agricultural enterprises effectively.
Agriculture is exposed to unpredictable weather patterns, pests, diseases, fluctuating commodity prices and market disruptions. These factors can affect farmers’ incomes and their ability to repay loans.Lending institutions must therefore consider the risks associated with different agricultural value chains before extending credit.
SACCOs could strengthen their lending models through agricultural insurance partnerships, proper borrower assessments, financial literacy programmes and continuous monitoring of financed enterprises.They also need to establish transparent loan application procedures and ensure that agricultural credit reaches viable businesses rather than being diverted to unrelated expenditure.
Affordable interest rates must also be balanced against the cost of mobilising funds, maintaining liquidity and protecting members’ savings.
Effective governance, accountability and professional management will consequently be essential if SACCOs are to manage larger agricultural financing portfolios.
Building a sustainable agricultural financing ecosystem
The government’s proposed KSh 2.2 billion on-lending facility provides an opportunity to strengthen the relationship between cooperative finance and agricultural development.
However, its success will depend on how effectively the money reaches productive enterprises and whether beneficiaries can generate sufficient returns to repay their loans and expand their businesses.
The Central Bank of Kenya’s September 2026 Agricultural Sector Survey provides an important indication of the growing relevance of SACCOs in this space. It found that 32 per cent of sampled farmers who had accessed credit reported borrowing from SACCOs, compared with 17 per cent in July 2026.
The findings suggest that SACCOs already feature in farmers’ financing choices, although there is still room to expand their contribution.
For Kenya, strengthening SACCO-led agricultural financing could help connect rural savings with productive investments, support young entrepreneurs and improve the financial capacity of smallholder farmers.
Ultimately, the transformation of agriculture requires a financing system that understands the business realities of farming. By combining affordable credit, enterprise development, agricultural expertise and market access, SACCOs could become important partners in building a more commercially viable and resilient agricultural sector.

Author: Moureen Koech
Moureen Koech is a passionate Digital Journalist, an adept Agribusiness Writer with a keen eye for news and an impactful story-teller,whose stories provide key value to Agripreneurs and stakeholders in the Agricultural sector